August 2026/Money + Home
How I bought my first home for $545 out of pocket
A $524,000 house, a $10,480 earnest-money check, and $9,935 of it back in my hand at closing. Here is every line of it.
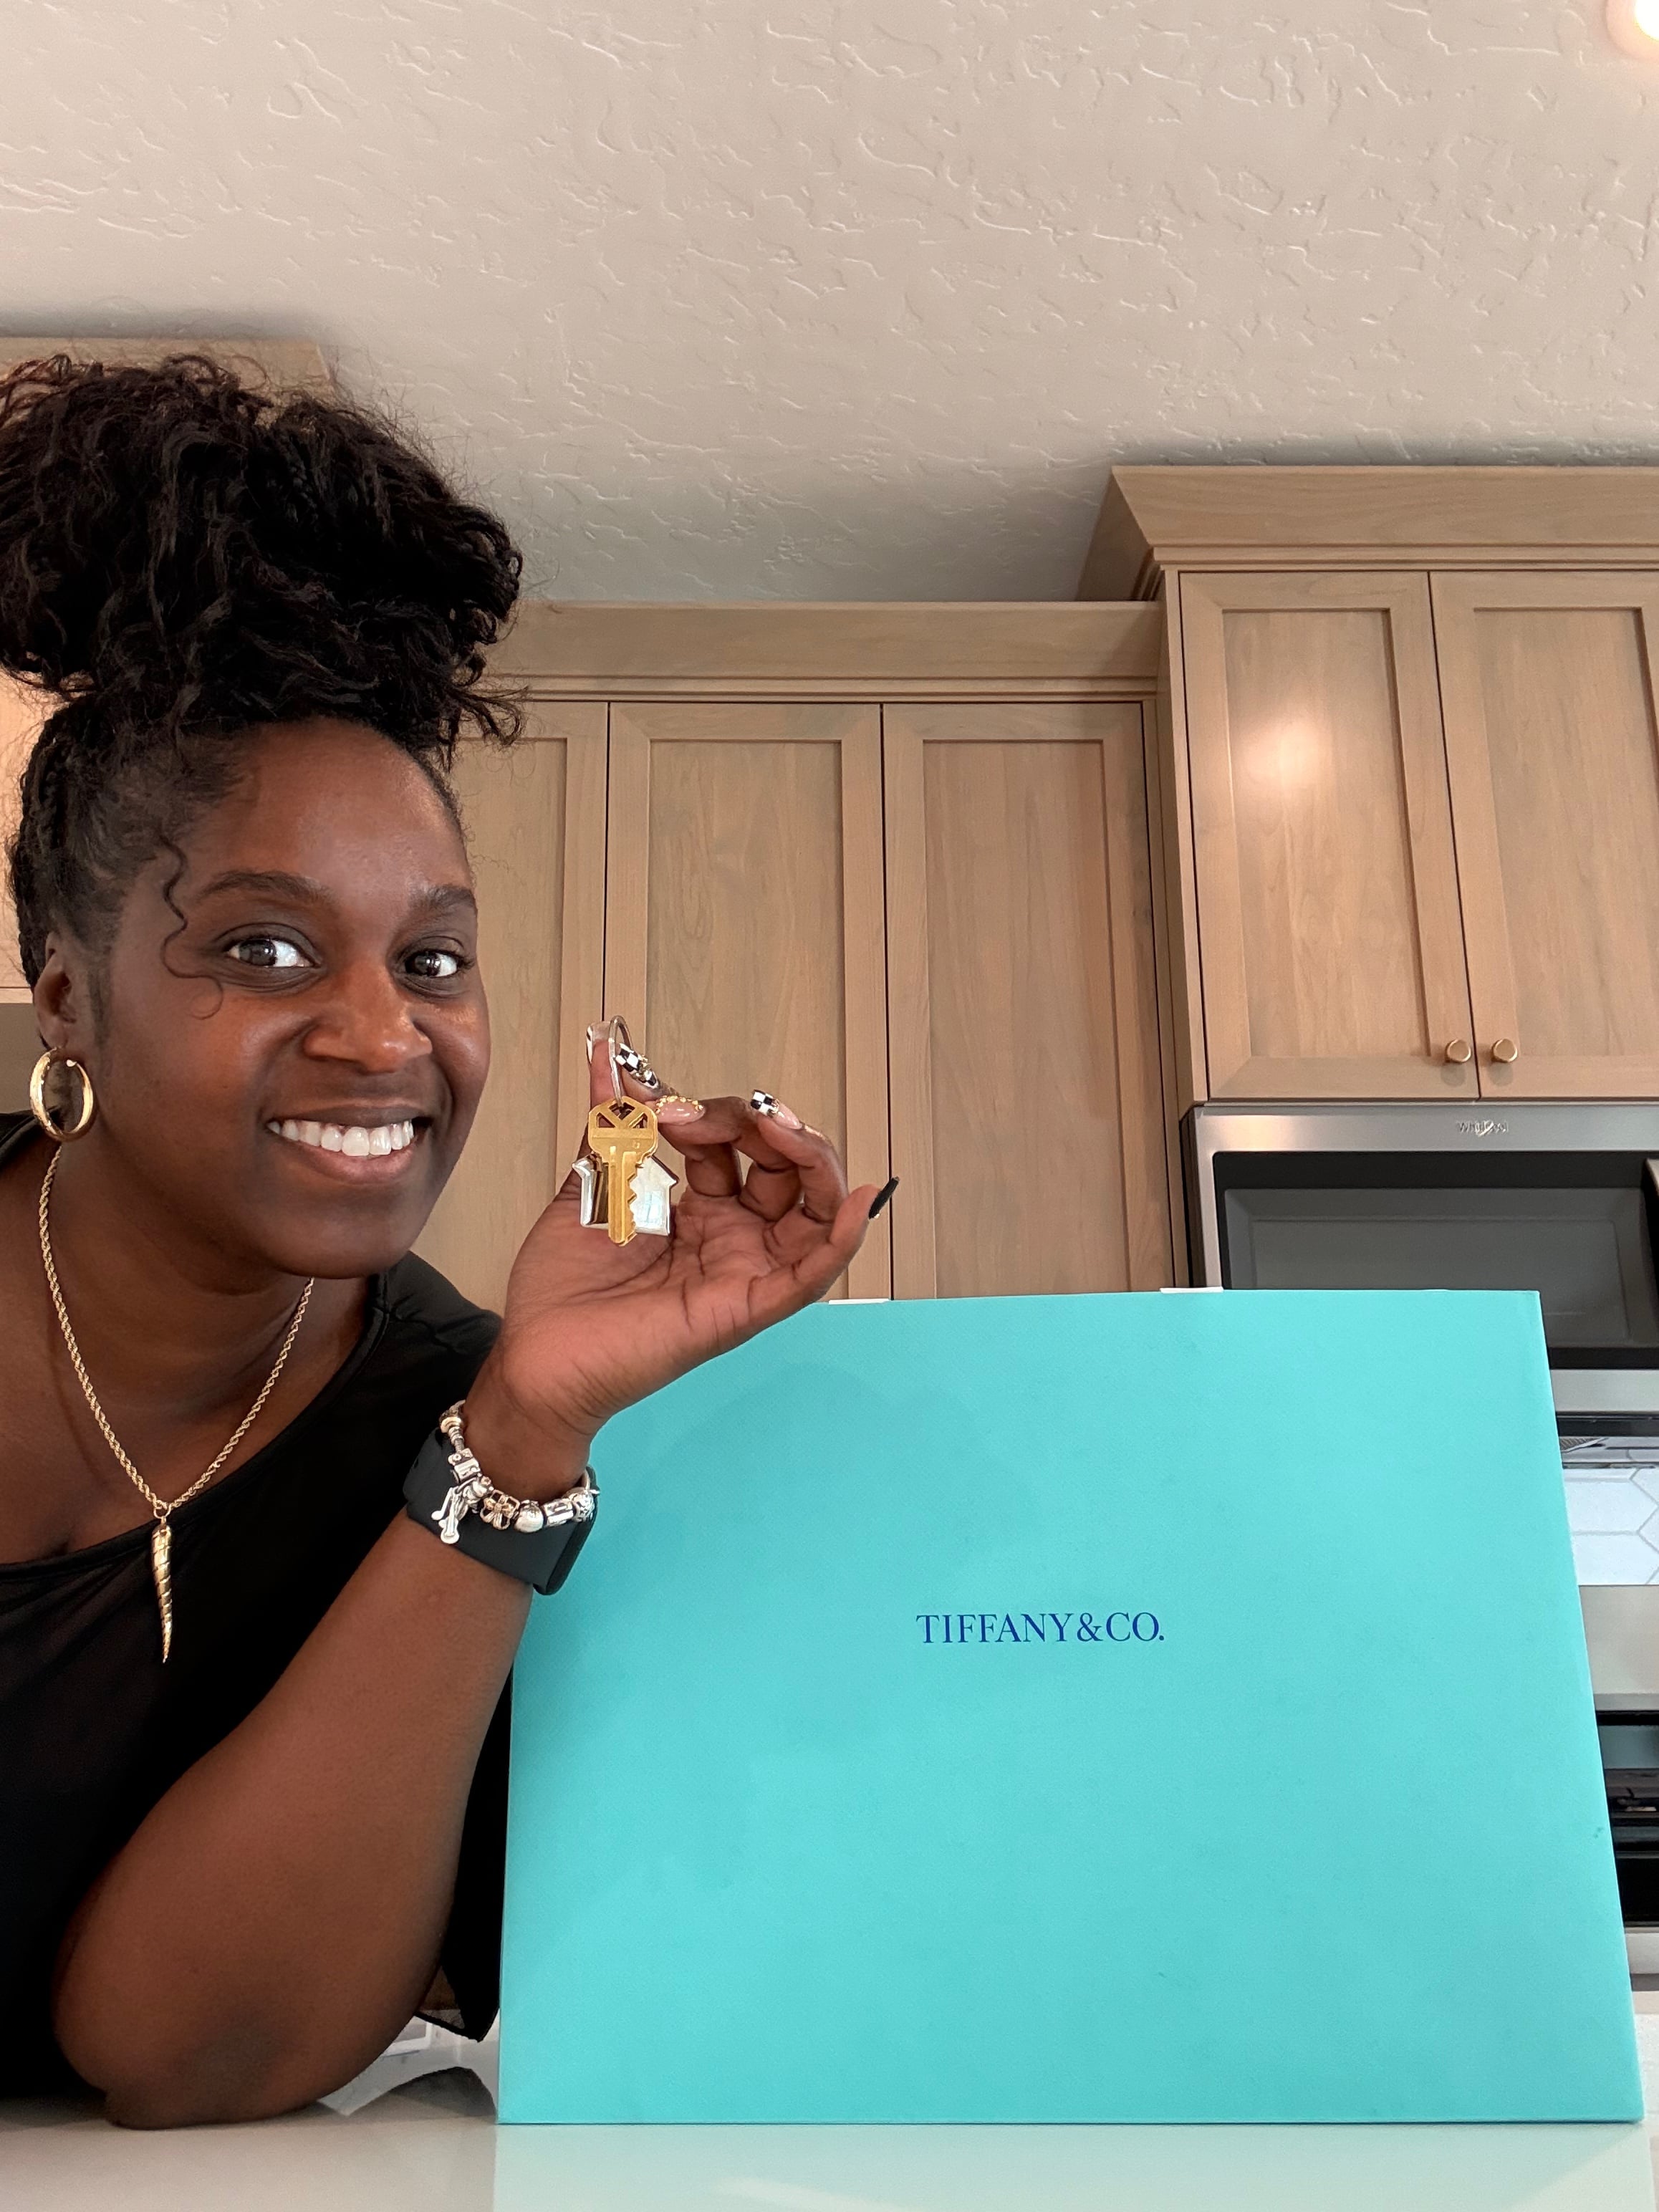
I bought my first home in the Boise area for $524,000. It was a quick move-in new-construction home from a national builder. My net earnest money applied at closing was $545.
Before I explain how, let me say the part that matters most: this is not a story about buying a half-million-dollar house with $545 to your name. I was financially prepared before I bought. Good credit, stable income, and roughly six months of reserves. I had been seriously preparing for nine to twelve months, and homeownership had been a goal long before that.
What the $545 actually represents is a transaction I structured on purpose, using programs and incentives I made a point of understanding before I needed them. That’s the repeatable part. Here’s all of it.
01
The $25,000 decision most buyers never hear about
I came into the process already preapproved with an outside lender, which felt like the responsible thing to have done. Then I found out the builder’s incentive worked in tiers: roughly $15,000 in seller credits if I brought my own financing, or $25,000 if I qualified through one of its preferred lenders.
That is a $10,000 swing on the same house. I qualified through Guild Mortgage and took the full $25,000.
I want to be careful here, because “use the builder’s lender” is not universally good advice. A preferred lender’s rate or fees can eat the difference. What I did was compare, not comply.
And when I compared, the monthly payments landed almost identically — about $7 a month apart, slightly in my favor with the preferred lender. Seven dollars is noise either way.
The real difference showed up in what came back to me at the closing table. With the preferred lender I got $9,935 of my earnest money returned. With my original lender, the estimated cash back to me was $4,772.16 — about $5,163 less in my pocket.
So the decision wasn’t about the rate at all. On the payment, the two options were effectively a tie. The thing that separated them was over five thousand dollars of my own cash staying with me instead of going to the table. That’s the kind of difference you only see if you make both lenders put the whole picture in writing.
02
How the down payment stayed out of my savings
I used an FHA loan paired with a program called Down Payment Assistance for Idaho Homebuyers, through the Idaho Housing and Finance Association. The assistance let the required down payment be financed rather than pulled out of the money I’d spent years saving. It comes as a second loan tied to the financing, so it isn’t free — it’s a trade. I chose to trade a second loan for keeping my liquidity intact.
That was my biggest priority in the whole transaction. I did not want to hand over a large portion of my savings for a down payment and then another chunk for closing costs if the purchase could be responsibly structured a different way. Cash in a house is cash you cannot reach when a water heater fails or your income pauses.
There was also a qualification detail I didn’t engineer but did benefit from. At closing I’d been with my employer about one year and nine months, so my income was averaged over 24 months. That average kept my qualifying income within the limits for the assistance program. It worked in my favor, and it’s a good example of why the details of how you’re underwritten matter as much as the headline numbers.
03
Where the $545 comes from
The builder required a 2% earnest-money deposit. On $524,000 that was $10,480 — real money, out of my account, well before closing.
The $25,000 seller credit then covered my eligible closing costs, and the credit left over went toward buying down my interest rate. With the down payment financed through the assistance program and the closing costs and buydown handled by the credit, there was very little left for my earnest money to cover. So most of it came back.
The math, plainly
Purchase price
$524,000
Seller credit (preferred-lender tier)
$25,000
Earnest money paid (2%)
$10,480
Earnest money returned at closing
− $9,935
Net earnest money applied
$545
One thing I deliberately leave out of that figure: I paid $743 separately for my home inspection. Inspection costs vary by property, location, inspector, and what a buyer chooses to inspect, so it isn’t part of what happened to my earnest money at closing. It was its own due-diligence expense, and it was worth every dollar.
04
New construction still needs inspecting
Because I bought a quick move-in home, I wasn’t in the process early enough for stage inspections like pre-drywall. The walls were already closed. So I bought a more extensive new-home inspection package and added checks on top of it, including moisture.
I’ve also been advised to have the home inspected again around the ten-month mark, while builder warranty coverage still applies. I absolutely plan to do it. Brand new does not mean nothing is wrong.
05
The agent mattered more than I expected
My agent was Donna Polk with HomeFound in the Boise area, and she was phenomenal. Proactive, informative, and deliberate about making sure I understood what was happening at every stage. She repeatedly brought things to my attention that I wouldn’t have known to ask about.
At one point I left the country while the transaction was underway. She kept everything moving. I recommend her without hesitation.
The point was never the $545. It was knowing which levers existed before I needed them.
What you can take from this
- Ask what the incentive is worth on both paths, then compare cash at closing — not just the rate. My two options were about $7 a month apart — effectively a tie — but over $5,000 apart in cash back at closing ($9,935 versus an estimated $4,772.16). The payment comparison alone would have told me nothing. Neither number alone would have told me that.
- Look up your state’s housing agency by name. Mine was the Idaho Housing and Finance Association. Nearly every state has one, and down-payment assistance is a real program with real income limits, not a rumor.
- Protect your liquidity on purpose. Structuring the purchase to preserve savings was a choice, not an accident. Decide before you shop how much cash you refuse to part with.
- Inspect the new build anyway. Especially a quick move-in, where you missed the stages. And put the ten-month re-inspection on your calendar now.
- Hire the agent who over-explains. The value isn’t opening doors. It’s telling you what you didn’t know to ask.
Your move.
Pick one thing this week. Search your state housing agency’s name and read their first-time buyer page. Or pull your credit. Or write down, honestly, how many months of reserves you have. Nine to twelve months of preparation is what stood between me and this house, and none of it started with a purchase — it started with finding out what I didn’t know. You can start that today.
Who was involved
Agent: Donna Polk, HomeFound (Boise, ID) · Original lender: Guild Mortgage · Down payment assistance: Down Payment Assistance for Idaho Homebuyers, Idaho Housing and Finance Association (also took over servicing) · Loan type: FHA. The loan transferred to the Idaho Housing and Finance Association for servicing about one payment in.
This article is educational and general in nature and describes one transaction; it is not a recommendation for your situation. Down payment assistance terms, income limits, rates, and incentives change and vary by state, program, and lender. Sherika Ralliford is an Investment Adviser Representative of Desert Rose Capital Management, a registered investment adviser; registration does not imply any level of skill or training. Full disclosures.