September 2026/Money + Life
The plan that could have existed
My mother was diagnosed with early-onset Alzheimer’s at 56. I found out what planning could have been in place beforehand only after it was too late to put it there.
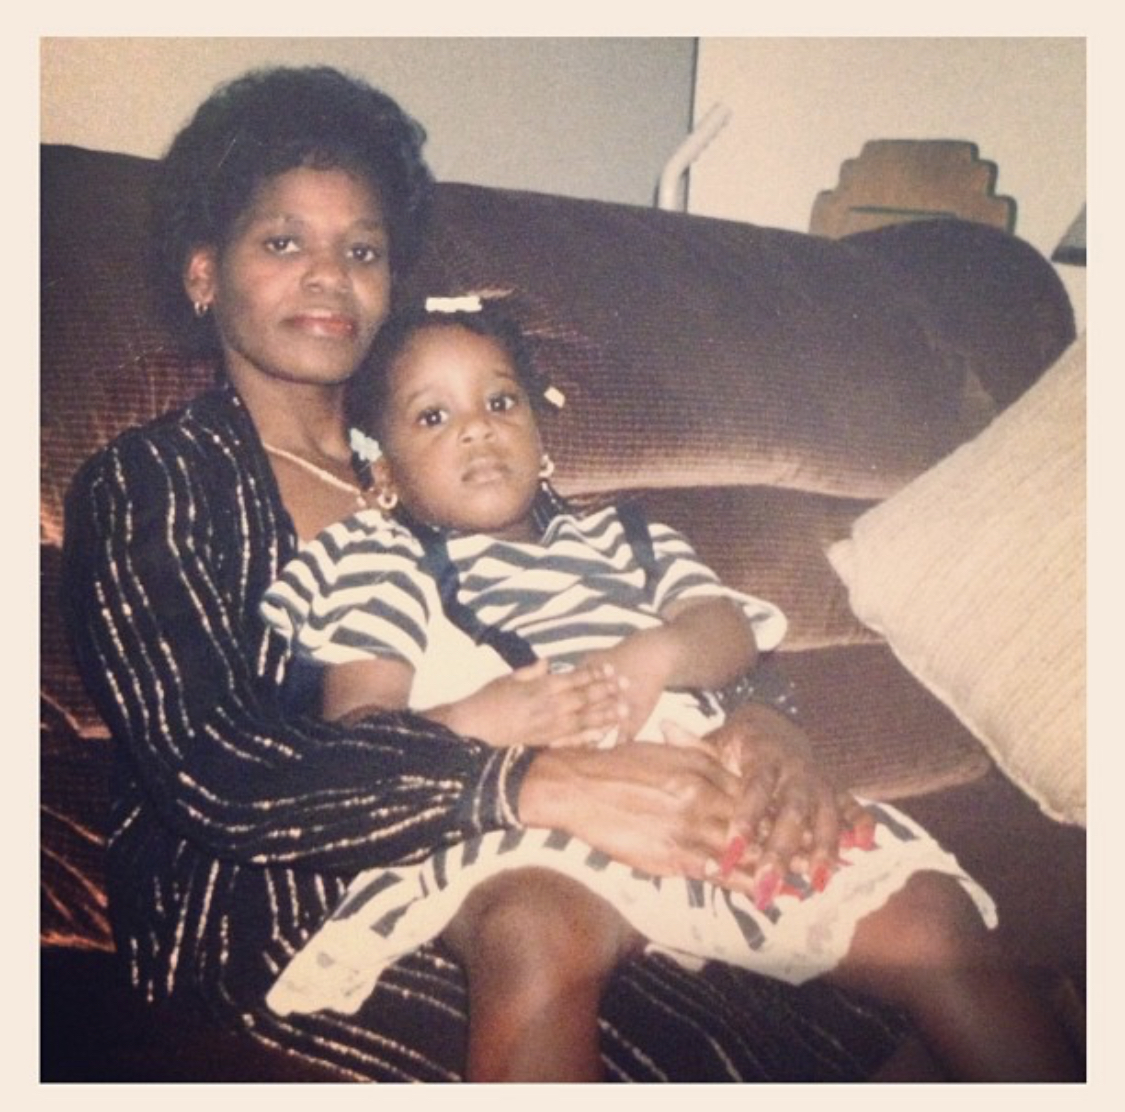
I was 28 and working in compliance at AT&T’s corporate office when my mom was diagnosed with early-onset Alzheimer’s disease. She was 56.
For about the first two and a half years, we managed. Then she declined to the point of wandering at night, and the amount of care she needed stopped fitting inside a life I also had to work in. AT&T ran on seniority and I was still low on that list, in a 24/7 call-center environment. There was no version of that schedule that bent around a mother who needed watching overnight.
So I pivoted my career. Not because I’d found a calling, but because I had become a caregiver and needed a job that would let me be one.
That pivot landed me at Prudential. I got my Series 6 and my insurance license, and I started learning the mechanics of an industry I had never paid attention to.
01
What I found out too late
Within months I ran into something that stopped me cold: life insurance policies with living benefits and accelerated benefit riders. Provisions that, under certain conditions, let a person access a portion of their own policy while they are still alive and ill.
If the right planning had existed before my mother’s diagnosis, there potentially could have been money available to help with her care, and possibly even to allow me to be compensated while caring for her. It wasn’t in place, and by the time I understood it existed, she was already past the point where anything could be put in place.
The painful part wasn’t that somebody had made a bad financial decision. It was that we simply didn’t know.
My mother thought of herself as a saver. She did save. But what she had accumulated wasn’t enough to fundamentally change what happened when her health changed.
02
The question that stayed
The other thing I understood that year was quieter and harder. I was not living with my mother while I figured out adulthood anymore. She was going to be living with me. I was going to be responsible for handling things.
I entered financial services almost by accident. I stayed because of a question that started that year and has never really left:
What else don’t I know?
This is not an argument for buying life insurance. The story is what happens when you discover planning possibilities after the moment when they could have helped you most, and why that made me obsessed with learning what else exists.
I can’t go back and put a plan in place for my mother. What I can do is refuse to let the next family find out too late, which is most of what my career has been since.
What you can take from this
- Most planning gaps are information gaps, not discipline gaps. Ask what options exist for the situation you’re most afraid of, before you’re in it.
- Almost everything worth putting in place has to be put in place while you’re healthy. Eligibility runs on your health, and you only have it until you don’t.
- Being a saver is not the same as being prepared for a specific event. Ask what you are actually saving against, and whether the amount matches it.
- If you own a life insurance policy, find out what it does while you’re still alive. Living benefits and accelerated benefit riders are common and rarely read.
- If you may one day care for a parent, that is a financial plan too — yours and theirs. Have the conversation while it’s still a hypothetical.
Your move.
Pick the scenario you’d least want to face — a parent’s diagnosis, your own, a long illness — and spend one hour this week finding out what planning exists for it. Not buying anything. Just finding out. I didn’t know any of it at 28, and finding out was the whole turning point. You get to find out before you need it.
What’s happening now
September is Life Insurance Awareness Month. There’s something in motion for it. See what’s happening now →
This article is educational and general in nature and describes personal experience; it is not a recommendation for your situation. Policy features, riders, costs, and eligibility vary by carrier, state, and health status, and insurance guarantees are subject to the claims-paying ability of the issuing company. Sherika Ralliford is an Investment Adviser Representative of Desert Rose Capital Management, a registered investment adviser; registration does not imply any level of skill or training. Full disclosures.